Every Filipino who has ever bought a property on installment — whether through a developer's in-house financing scheme or a pre-selling payment plan — has rights under Philippine law that many buyers do not know exist. Republic Act 6552, more commonly known as the Maceda Law, is one of the most important pieces of consumer protection legislation ever passed for property buyers in the Philippines, and yet it remains one of the least understood.
If you have been paying for a property and are now unable to continue, or if a developer is threatening to cancel your contract, this law may protect you in ways you were never told about. This guide explains exactly what the Maceda Law covers, what it entitles you to, and how to assert your rights if a developer attempts to cancel your purchase.
What Is the Maceda Law?
Republic Act 6552, officially titled the "Realty Installment Buyer Act," was signed into law on August 26, 1972 by President Ferdinand Marcos Sr. It is named after its principal author, Senator Ernesto Maceda. The law was created in direct response to the widespread practice of developers cancelling buyers' contracts without refund after years of installment payments — a practice that left countless Filipino families homeless and penniless.
At its core, the Maceda Law does three things: it gives installment buyers a grace period to catch up on missed payments before a developer can cancel the contract, it entitles buyers to a cash refund if the contract is ultimately cancelled after two or more years of payments, and it requires developers to give formal written notice before any cancellation can take effect.
The law applies to the sale of residential real estate on installment — house and lot, condominium units, and residential lots — where the buyer has paid at least two years of installments. It is a mandatory law, meaning its protections cannot be waived by contract. Any provision in a Contract to Sell that strips away Maceda Law rights is null and void.
Developers sometimes include clauses in Contracts to Sell stating that the buyer waives their right to refund or grace period in case of default. Under Philippine law, such waivers are unenforceable. The Maceda Law's protections are granted by statute and cannot be contracted away. If a developer tells you the law does not apply because of a clause in your contract, that is legally incorrect.
Who Does the Maceda Law Cover?
Understanding the scope of the law is critical — it does not apply to all property transactions.
The following transactions are covered: developer installment sales for house and lot, condominium units, and residential lots. The following are not covered: bank home loans (mortgaged property), which are governed by the bank contract and Civil Code; Pag-IBIG housing loans, which are governed by HDMF rules and regulations; and commercial or industrial property, as the law covers residential property only. Lease-to-own arrangements fall on a case-by-case basis depending on the contract structure.
The most important takeaway: the Maceda Law applies specifically to direct installment transactions with a developer. If you took out a bank loan or a Pag-IBIG loan to purchase the property — meaning the bank or Pag-IBIG paid the developer and you are now repaying the lender — the Maceda Law does not govern your relationship with the bank. Your rights in that case are determined by your loan agreement, the bank's policies, and the general provisions of the Civil Code.
However, the Maceda Law is still highly relevant to financed buyers during the pre-selling period: most pre-selling buyers pay the down payment portion in installments directly to the developer before the bank loan kicks in at turnover. Those down payment installments are covered by the Maceda Law.
The Two-Tier Protection System
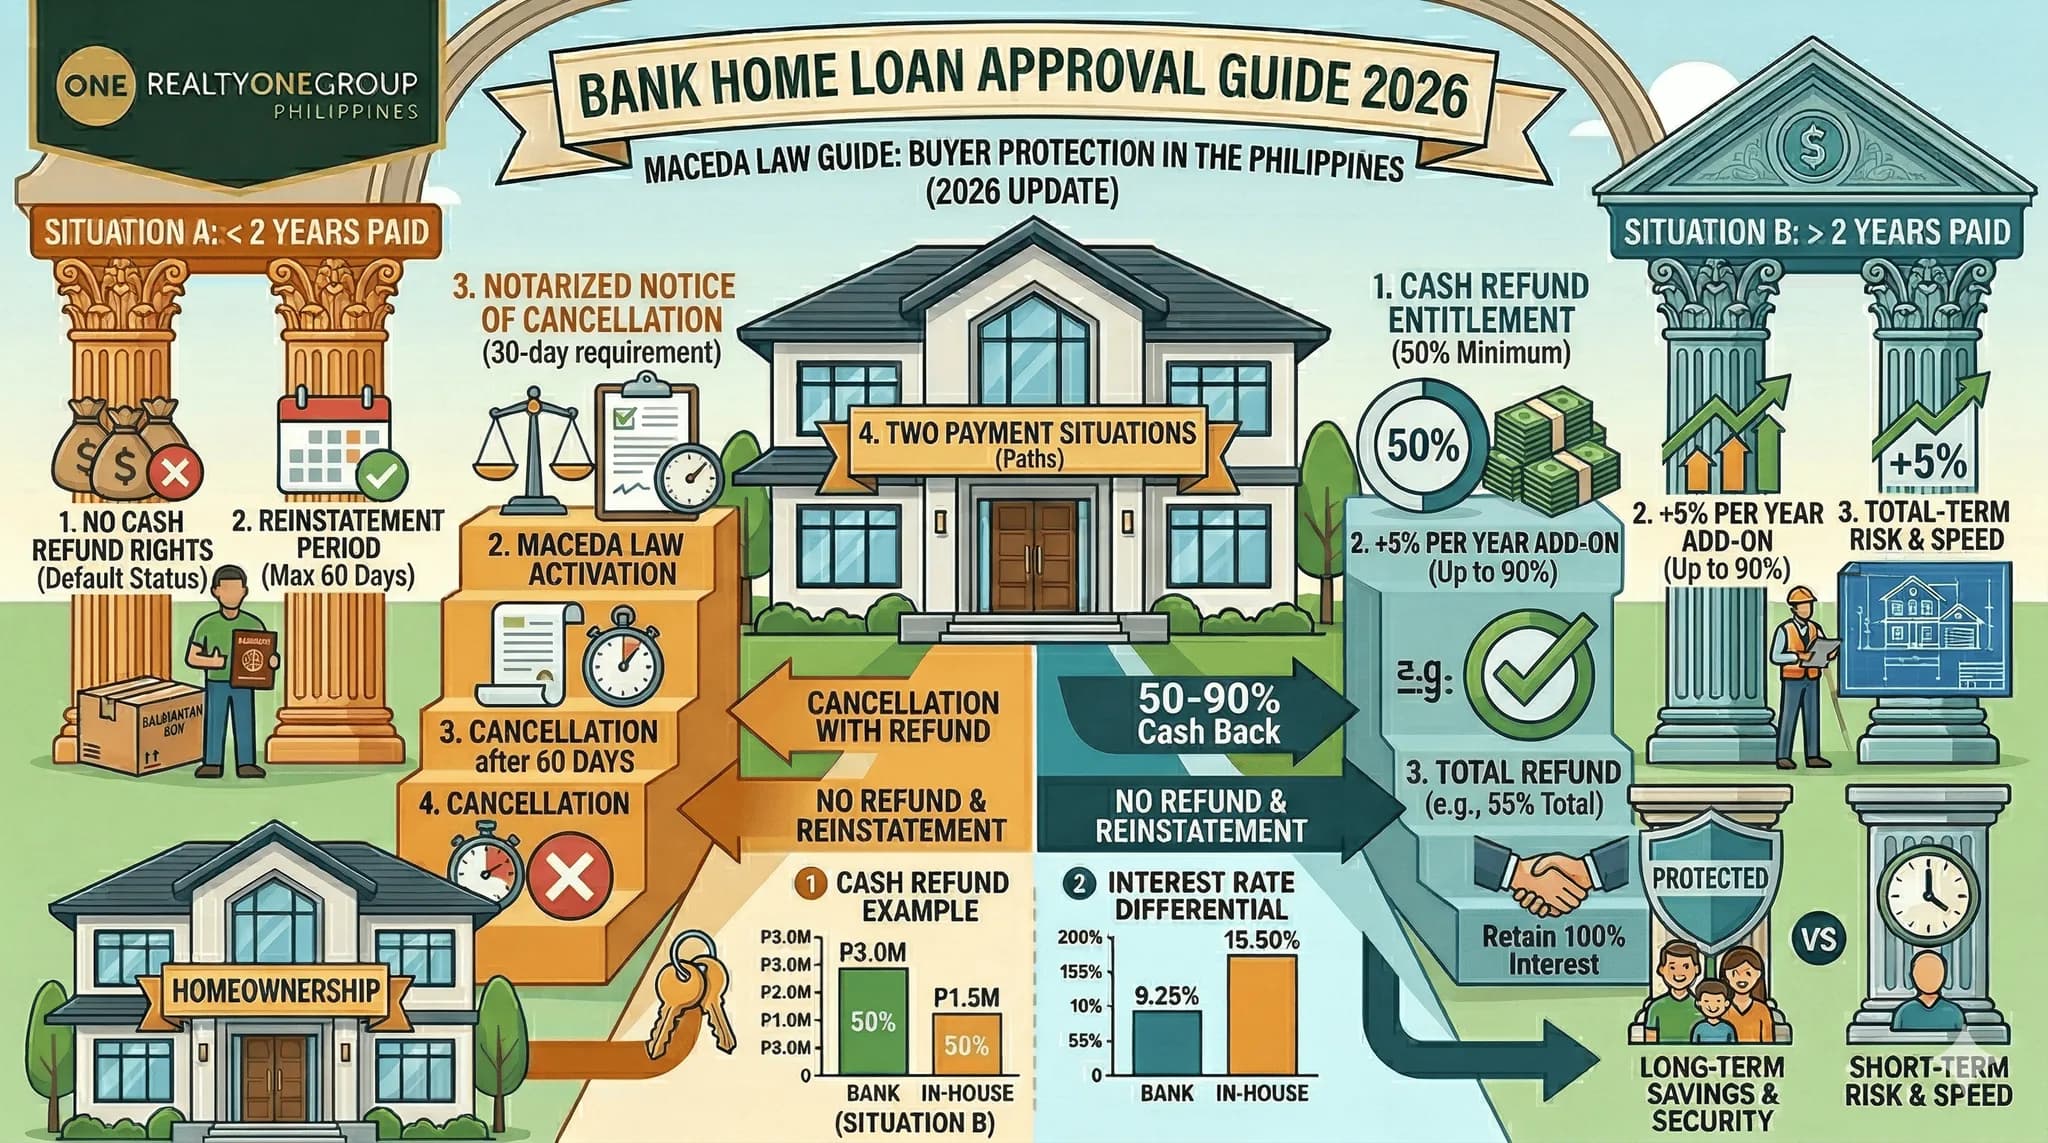
The Maceda Law creates two distinct tiers of protection depending on how long you have been paying. The threshold is two years of installment payments.
Tier 1: Less Than Two Years of Payments
If you have been paying for less than two years and you default, the developer is not required to give you a grace period or a cash refund. However, the developer must still give you a 60-day written notice before cancelling the contract. If you are able to catch up on all missed payments within that 60-day window, the contract must be reinstated.
This is important: even with less than two years of payments, a developer cannot simply cancel your contract overnight. The 60-day notice requirement is mandatory regardless of the number of installments paid.
Tier 2: Two or More Years of Payments
If you have been paying for two years or more, the full force of the Maceda Law kicks in. You are entitled to all three major protections: a grace period, a cash refund if cancelled, and a mandatory 30-day written notice before cancellation can be effected.
The grace period is one month for every year of installment payments made. So if you have paid for five years, you are entitled to a five-month grace period during which the developer cannot cancel your contract, even if you have not made any payments.
The 30-day notice must be a formal written notice sent by the developer. The grace period begins running from the date the notice is received. If you make good on the arrears within the grace period, the contract must be kept alive.
The grace period under the Maceda Law is not something you apply for or request. It is automatically triggered by the developer's notice of default. Once you receive the notice, the grace period begins running. You should notify the developer in writing that you are invoking your Maceda Law rights and intend to settle within the grace period.
Grace Periods and Refund Rights: The Full Schedule
Here is the complete schedule of rights under the Maceda Law depending on how many years of installments you have paid.
Less than 2 years — Grace period: none (but 60-day notice required). Refund on cancellation: no cash refund.
2 years but less than 5 years — Grace period: 1 month per year of payments. Refund: 50% of total payments made.
5 years but less than 10 years — Grace period: 1 month per year of payments. Refund: 50% + 5% per year beyond 5 years (max 90%).
10 years or more — Grace period: 1 month per year of payments. Refund: 90% of total payments made.
The grace period runs from the date of the developer's formal written notice.
A few important clarifications on the refund schedule. The "total payments made" that forms the basis of the refund calculation includes all installments paid on the purchase price, but does not include interest, penalties, or other charges. The refund is on the principal payments toward the property price itself.
The additional 5% per year beyond five years (up to a maximum of 90%) is calculated as follows: if you paid for seven years, your refund entitlement is 50% plus 5% times two additional years beyond five, giving you 60% of total principal payments made. At ten years, you reach the 90% ceiling.
Real-World Refund Scenarios
Suppose you purchased a condominium unit for ₱3,000,000 under a developer in-house installment plan at ₱20,000 per month.
2 years paid — Total paid: ₱480,000. Refund %: 50%. Refund amount: ₱240,000. Developer keeps: ₱240,000.
5 years paid — Total paid: ₱1,200,000. Refund %: 50%. Refund amount: ₱600,000. Developer keeps: ₱600,000.
7 years paid — Total paid: ₱1,680,000. Refund %: 60%. Refund amount: ₱1,008,000. Developer keeps: ₱672,000.
10 years paid — Total paid: ₱2,400,000. Refund %: 90%. Refund amount: ₱2,160,000. Developer keeps: ₱240,000.
Figures are for illustration only and exclude interest and penalties.
The longer you have been paying, the more the law protects you. A buyer who has paid for ten years and is forced into cancellation walks away with 90% of their total principal payments — the developer only retains 10%. This is a fundamental shift from how the market operated before the Maceda Law, when developers could keep 100% of all payments made.
Note that the refund must be paid within 30 days from the date of cancellation. If the developer fails to pay within this window, the cancellation itself may be challenged as invalid.
The Maceda Law refund is based on the actual installment payments made toward the purchase price — not the total contract price. Amounts paid as interest under in-house financing arrangements, penalties for late payment, reservation fees, and processing charges are generally not included in the refundable amount. Always request a detailed payment ledger from the developer showing the breakdown between principal and interest before making any claims.
The Cancellation Process: What Developers Must Do
The Maceda Law sets out a mandatory procedure that developers must follow before a contract cancellation is legally valid. A cancellation that does not follow this procedure is void — meaning you may continue to assert your rights to the property even after the developer claims to have cancelled the contract.
Step 1: Formal Written Notice
The developer must send a formal written notice of default to the buyer. For buyers with two or more years of payments, this notice must give at least 30 days before cancellation can take effect. For buyers with less than two years of payments, the notice period is 60 days. The notice must be sent to the buyer's address on record — if the developer does not have your current address because you failed to update them, you may still have grounds to challenge a cancellation on procedural grounds.
Step 2: Notarization of the Notice
Under RA 6552, the notice of cancellation must be by notarial act — meaning it must be a notarized document, not simply a letter or an email. An unnotarized cancellation notice is procedurally defective and may render the cancellation invalid. This is a technical requirement that developers sometimes overlook, and it is one of the most common grounds on which buyers successfully challenge cancellations.
Step 3: Grace Period Must Expire Unused
The developer cannot effect cancellation while the grace period is still running. If you make any payment — even partial — toward the arrears within the grace period, this stops the cancellation clock. The developer must accept any payment made within the grace period and cannot refuse it.
Step 4: Refund Payment Within 30 Days
If the contract is ultimately cancelled, the developer must pay the refund within 30 days from the date of cancellation. Failure to do so within this window opens the developer to legal liability and may give the buyer grounds to contest the validity of the cancellation itself.
When you receive a cancellation notice, immediately send a written reply by registered mail invoking your Maceda Law rights. State the number of years and months you have been paying and calculate your grace period. Bring all payment records to a lawyer for review. Do not simply accept the developer's cancellation as final — verify that they followed all procedural requirements. Many developers count on buyers not knowing these rules.
The Maceda Law and Pre-Selling Properties
The Maceda Law is especially relevant in the context of pre-selling properties — units purchased before construction is complete and paid through a developer installment scheme during the construction period.
In a typical pre-selling setup, buyers pay the down payment portion (usually 10–30% of the contract price) in monthly installments over the construction period of two to five years. These payments are made directly to the developer, not to a bank. This is a classic installment sale covered by the Maceda Law.
Situations where this becomes critical include: job loss or income disruption during the construction period, unit turnover delays that push buyers to reconsider their purchase, significant changes in the buyer's financial situation, or disputes with the developer over construction quality or delivery timelines.
What If the Developer Is the One Defaulting?
The Maceda Law primarily addresses buyer defaults, but Philippine law also provides remedies when it is the developer who fails to deliver. Under the Condominium Act, the Subdivision and Condominium Buyers' Protective Decree (PD 957), and HLURB / DHSUD regulations, buyers have the right to demand a full refund with interest if the developer fails to deliver the unit within the promised timeline. These are separate rights from the Maceda Law but are equally important and worth knowing.
Presidential Decree 957, known as the Subdivision and Condominium Buyers' Protective Decree, works alongside the Maceda Law. PD 957 governs developer obligations — timely delivery, proper documentation, and adherence to approved plans. If your developer is in default of their obligations to you, PD 957 may entitle you to a full refund with interest regardless of how long you have been paying. Always consider both laws when evaluating your rights.
How to Assert Your Maceda Law Rights
If you find yourself in a situation where your Maceda Law rights may be relevant — whether you are in default, have received a cancellation notice, or simply want to understand your options — here is the practical path forward.
Gather all your payment records. Collect every official receipt (OR) for every payment you have made to the developer. If you cannot find your ORs, request a certified statement of account from the developer showing all payments received. This is the foundation of your Maceda Law claim.
Calculate your years of payment and entitlements. Count the number of years from your first payment to today. Use the schedule in the Grace Periods section to determine your grace period and refund entitlement. Write this down before any communication with the developer.
Respond in writing to any cancellation notice. As soon as you receive a notice of default or cancellation, respond immediately by registered mail invoking your Maceda Law rights. State your payment history, your computed grace period, and your intention to settle within that period. Keep a copy of everything you send.
Verify the procedural requirements. Check whether the cancellation notice was notarized. Check whether the grace period has actually lapsed. Check whether you made any payment within the grace period that the developer may have refused or ignored.
Consult a lawyer before signing anything. If the developer is pressuring you to sign a deed of cancellation or to acknowledge the termination of your contract, do not sign without legal advice. Signing a deed of cancellation voluntarily may waive your right to contest the cancellation later.
File a complaint with DHSUD if the developer is non-compliant. The Department of Human Settlements and Urban Development (DHSUD, formerly HLURB) has jurisdiction over disputes between buyers and developers. Filing a complaint is relatively straightforward and does not require expensive litigation. DHSUD has the power to order refunds, reinstate contracts, and penalize developers who violate the Maceda Law.
What the Maceda Law Does Not Cover
It is equally important to understand the boundaries of the Maceda Law so you do not rely on it in situations where it does not apply.
Bank and Pag-IBIG loans. If you borrowed money from a bank or Pag-IBIG to buy your property, your installment payments are to the lender, not the developer. The Maceda Law does not apply to this relationship. If you default on a bank loan, the bank can foreclose on the mortgage under the terms of your loan agreement and the relevant foreclosure laws.
Commercial, industrial, and office properties. The law explicitly covers residential real estate only. Office condominiums, commercial lots, retail spaces, and industrial property are not covered.
Fully paid properties. Once you have completed all installment payments and the title has been transferred to your name, the Maceda Law no longer has ongoing relevance to your transaction.
Lease agreements. Month-to-month or fixed-term leases are not installment purchase transactions and are not covered. Lease-to-own arrangements may fall into a grey area depending on how the contract is structured.
Purchases from private individuals. The Maceda Law was designed to address the power imbalance between large developers and individual buyers. Sales between private individuals on installment may have different legal treatment under the Civil Code.
The best time to understand the Maceda Law is before you sign a Contract to Sell — not after a dispute arises. When reviewing a developer's contract, check that it does not include any clause purporting to waive your Maceda Law rights. If it does, ask the developer to remove it. A legitimate developer will have no objection. If they refuse, that is a red flag worth taking seriously.
The Maceda Law is one of the most powerful consumer protection tools available to Filipino property buyers — but only to those who know it exists. If you are buying a property on installment directly from a developer, this law is your safety net. It cannot be taken away by contract, it scales in your favor the longer you have been paying, and it requires developers to follow a specific legal procedure before they can cancel your purchase.
Understanding the Maceda Law does not mean planning to default on your payments. It means buying with confidence, knowing that if circumstances beyond your control force you into difficulty, the law provides a structured and fair path forward. That knowledge alone is worth more than any clause in any contract.
If you believe your Maceda Law rights have been violated or if you need guidance on how to assert them, consult a licensed real estate lawyer or file a complaint directly with the DHSUD. You can also reach out to a licensed real estate broker who can point you to the right resources and professionals for your situation.
About the Author
Miguel Lorenzo V. Camero · Realty One Group Philippines
This article was written to share general knowledge about the Maceda Law and buyer protections on installment property purchases in the Philippines with fellow Filipinos who may not be familiar with their rights. It is shared in the spirit of education and community — because every Filipino deserves to understand the real path to homeownership. For property inquiries or real estate guidance, reach out through Realty One Group Philippines.
Disclaimer: This article is for general informational and educational purposes only. It is not legal advice and should not be relied upon as a substitute for consultation with a licensed attorney. The Maceda Law (RA 6552) and related Philippine statutes are subject to interpretation by the courts and relevant government agencies. Specific legal situations may vary. Always consult a qualified real estate lawyer and verify current regulations with the Department of Human Settlements and Urban Development (DHSUD) before taking any legal action.